CHFA Schools to Home for Jeffco Public Schools Employees
Jeffco is the second-largest district in Colorado with 143 schools, spread from Lakewood to Conifer. What the assistance is worth depends a lot on which end you buy in.

Yes, Jeffco Public Schools employees qualify for CHFA Schools to Home, and it is not limited to teachers. Any full-time employee of the 143 schools on CHFA's eligible-employer list qualifies whatever their job title, and only one borrower on the loan has to be the school employee.
On a $525,000 home that is roughly $105,000 of down payment help against a $420,000 first mortgage, with no monthly payment on the assistance and no mortgage insurance. Household income must be at or below $178,920, the minimum credit score is 620, and there is no purchase price limit and no first-time-buyer requirement. You repay the assistance plus a share of the home's appreciation when you sell or refinance.
with Zach Belloni, Speak Straight Mortgage
Jeffco Public Schools runs 143 schools, from Lakewood and Wheat Ridge through Arvada and Golden and up into Evergreen and Conifer. It is the second-largest district in the state and one of the largest employers on the west side of the metro.
Any full-time Jeffco employee qualifies for CHFA Schools to Home, which covers your down payment and eligible closing costs up to 25% of the first mortgage, deferred with no monthly payment. It is not a teachers-only program. Paras, bus drivers, custodians, nutrition and office staff, campus supervisors and district employees all count, and only one borrower on the loan has to work for the district.
All 143 Jefferson County R-1 schools on CHFA's eligible-employer list. Search yours. Working at any of them makes you eligible, whatever your job title is, and only one borrower on the loan has to be the school employee.
Work for a charter, a BOCES, or another Colorado district? The full statewide list is on our Colorado guide.
Every school in Jeffco Public Schools is on CHFA's eligible-employer list
All 143 schools in Jeffco Public Schools qualify: 123 district-run and 20 charters. Working at any of them counts, whatever your job title.
District-run schools (123)
- Adams Elementary School
- Alameda International Junior/Senior High School
- Arvada High School
- Arvada West High School
- Bear Creek High School
- Bear Creek K-8 School
- Bell Middle School
- Belmar School of Integrated Arts
- Bergen Elementary School
- Blue Heron Elementary School
- Bradford K8 North
- Bradford K8 South
- Brady Exploration School
- Campbell Early Learning Center
- Carmody Middle School
- Chatfield High School
- Columbine High School
- Columbine Hills Elementary School
- Conifer Senior High School
- Connections Learning Center on the Earle Johnson Campus
- Coronado Elementary School
- Creighton Middle School
- D'Evelyn Junior/Senior High School
- Dakota Ridge Senior High School
- Deane Elementary School
- Deer Creek Middle School
- Dennison Elementary School
- Devinny Elementary School
- Drake Junior High School
- Dunstan Middle School
- Dutch Creek Elementary School
- Edgewater Elementary School
- Eiber Elementary School
- Elk Creek Elementary School
- Evergreen High School
- Evergreen Middle School
- Everitt Middle School
- Fairmount Elementary School
- Falcon Bluffs Middle School
- Foothills Elementary School
- Foster Dual Language PK-8
- Fremont Elementary School
- Golden High School
- Governor's Ranch Elementary School
- Green Gables Elementary School
- Green Mountain High School
- Hackberry Hill Elementary School
- Hutchinson Elementary School
- JeffCo Remote Learning Program
- Jeffco Transition Services School
- Jeffco Virtual Academy
- Jefferson County Open Elementary School
- Jefferson County Open Secondary
- Jefferson Junior/Senior High School
- Ken Caryl Middle School
- Kendallvue Elementary School
- Kendrick Lakes Elementary School
- Kyffin Elementary School
- Lakewood High School
- Lasley Elementary School
- Lawrence Elementary School
- Leawood Elementary School
- Little Elementary School
- Longview High School
- Lukas Elementary School
- Lumberg Elementary School
- Mandalay Middle School
- Manning Options School
- Maple Grove Elementary School
- Marshdale Elementary School
- McLain Community High School
- Meiklejohn Elementary
- Miller Special Education
- Mitchell Elementary School
- Mortensen Elementary School
- Mount Carbon Elementary School
- Norma Anderson Early Learning Center
- Normandy Elementary School
- North Arvada Middle School
- Oberon Middle School
- Parmalee Elementary School
- Patterson International School
- Peak Expeditionary - Pennington
- Pomona Junior/Senior High School
- Powderhorn Elementary School
- Prospect Valley Elementary School
- Ralston Elementary School
- Ralston Valley Senior High School
- Red Rocks Elementary School
- Rooney Ranch Elementary School
- Rose Stein International Elementary
- Ryan Elementary School
- Secrest Elementary School
- Semper Elementary School
- Shaffer Elementary School
- Shelton Elementary School
- Sierra Elementary School
- Slater Elementary School
- Sobesky Academy
- South Lakewood Elementary School
- Standley Lake High School
- Stevens Elementary School
- Stober Elementary School
- Stony Creek Elementary School
- Stott Elementary School
- Summit Ridge Middle School
- Swanson Elementary School
- Three Creeks K-8
- Ute Meadows Elementary School
- Van Arsdale Elementary School
- Vanderhoof Elementary School
- Warder Elementary School
- Warren Tech
- Wayne Carle Middle School
- Weber Elementary School
- Welchester Elementary School
- West Jefferson Elementary School
- West Jefferson Middle School
- West Woods Elementary School
- Westgate Elementary School
- Westridge Elementary School
- Wheat Ridge High School
- Wilmot Elementary School
Charter schools (20)
- Addenbrooke Classical Academy
- Addenbrooke Classical Grammar School
- Collegiate Academy of Colorado
- Compass Montessori - Golden Charter School
- Compass Montessori - Wheat Ridge Charter School
- Doral Academy of Colorado
- Excel Academy Charter School
- Free Horizon Montessori
- Jefferson Academy Coal Creek Canyon
- Jefferson Academy Elementary
- Jefferson Academy Secondary
- Lincoln Charter Academy
- Montessori Peaks Charter Academy
- Mountain Phoenix Community School
- New America School
- Rocky Mountain Academy of Evergreen
- Rocky Mountain Deaf School
- Summit Academy
- Two Roads Charter School
- Woodrow Wilson Charter Academy
How the money actually works
The assistance arrives as a second mortgage with no monthly payment. Nothing is due on it while you live in the house. It comes due when you sell, refinance or pay off the first mortgage, or the home stops being your primary residence.
At that point you repay the assistance plus a share of the home's appreciation, which goes back to Colorado's Public School Permanent Fund. Your share of the gain matches the share of the price the fund put in, so if it covered 20% of the purchase you keep 80% of the growth. If the home has not appreciated, the appreciation piece is zero. We put your own numbers on paper before you sign anything, and the statewide guide walks through a full example.
What Jeffco Public Schools employees need to qualify
- Household income at or below $178,920
- Credit score of 620 or better
- A Fannie Mae conventional 30-year fixed on a home you will live in
- Single-family, PUD, condo or double-wide manufactured
- No first-time-buyer requirement, so a previous owner is fine
- CHFA homebuyer education plus the program's financial-commitment course
The west side is really three markets
Where you buy inside Jeffco changes the arithmetic more than in any other district on this list. Lakewood and Wheat Ridge still hold houses a $420,000 first mortgage reaches. Arvada and Golden run higher. Evergreen and Conifer are a different market again, with well and septic, wildfire insurance and a mountain commute in the winter.
The assistance covers the down payment in all three, but the insurance line is what surprises people up the hill, and it is part of the payment we quote rather than a footnote. Nick knows which pockets of Arvada and Lakewood still trade under the county median, which is where most Jeffco staff end up buying.
Start with the numbers, not an application
Schools to Home runs through CHFA participating lenders and it starts with a short conversation. We confirm your employer is on the list, run your income against the cap, and show you the assistance and the appreciation share side by side at the price you are actually shopping. Nothing is submitted anywhere until you say so.
See your Jeffco Public Schools numbers →
The other Denver-metro districts
Each one has its own page, its own school list and its own price ladder.
- Adams 12 Five Star Schools 53 schools
- Denver Public Schools 190 schools
Zooming out: the statewide guide covers every eligible Colorado school employer, and there are separate pages for Aurora and Colorado Springs.
Frequently Asked Questions
Can a Jeffco Public Schools employee use CHFA Schools to Home?
How much down payment help on a $525,000 Jeffco home?
Does it work for a home in Evergreen or Conifer?
What is the income limit for a two-earner Jeffco household?
What the assistance actually costs you
Schools to Home is not a grant. The state second mortgage is repaid in full when you sell, refinance, pay off the first mortgage, or stop living in the home — and on top of that you repay a fixed share of the appreciation. That share is the original second divided by the original purchase price, and it is locked at closing.
On a $400,000 purchase the first mortgage is $320,000 and the state second is $80,000, so the share is 20%. Sell seven years later at $491,950 and the gain is $91,950 — you repay the $80,000 plus $18,390 of appreciation. Against a conventional 3% down loan, which costs you $12,000 at closing and carries mortgage insurance until year 12, Schools to Home still leaves you roughly $31,652 ahead in that scenario — $12,000 you never put down, $55,014 of lower payments over seven years, less the $35,361 of equity the appreciation share costs you. A home that loses value owes no appreciation share, but the second is still repaid in full.
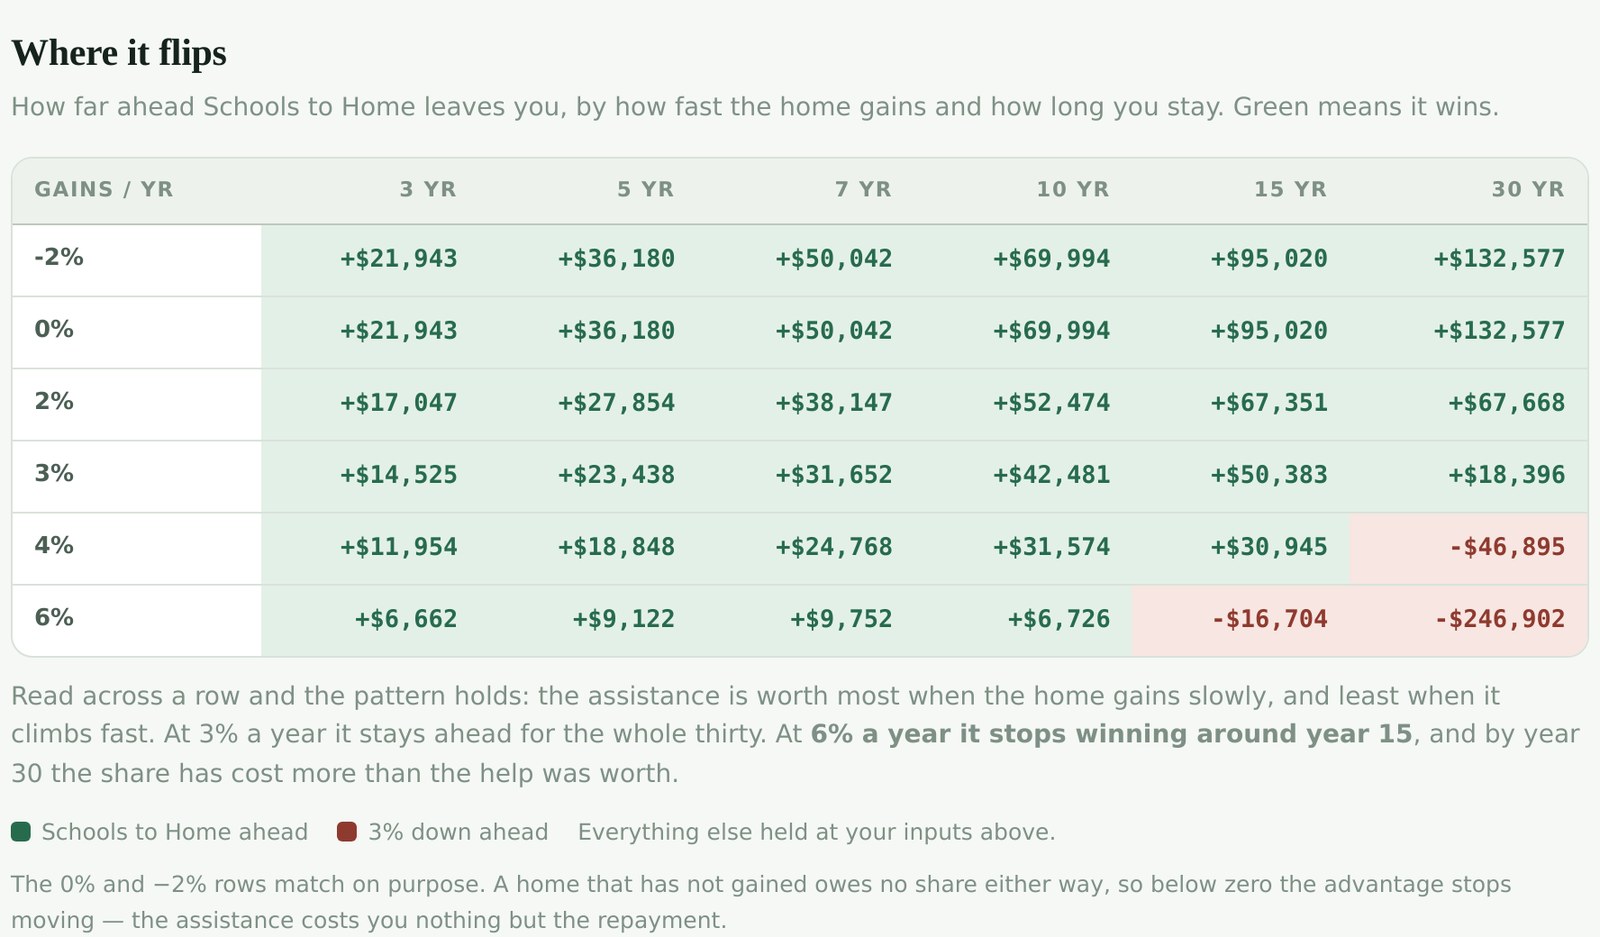
The balance shifts with how fast the home gains and how long you stay. At 3% a year the assistance stays ahead for the full thirty years; at 6% a year it stops winning between years 10 and 15. Put your own price, rate and timeline in below.
What the down payment help really costs you
Colorado pays your down payment and you skip mortgage insurance entirely — in exchange for a fixed slice of every dollar your home gains. Here is the trade, in your numbers.
Your situation
Change anything — everything below updates as you type.
After giving back the assistance and its share of the gain, Schools to Home still leaves you ahead by
Selling in year 7 at 3.0% a year. That counts the $12,000 you keep at closing, $55,014 of lower payments and no mortgage insurance, against $18,390 of appreciation owed on top of the $80,000 you borrowed.
What makes up that number
- Cash you keep at closing
- +$12,000
- Lower payments over 7 years, incl. no PMI
- +$55,014
- Equity given up at sale
- -$35,361
- Schools to Home ahead by
- +$31,652
Your payment starts about $662 a month lower, and you bring $12,000 less to the closing table. Set against that, you hand back $18,390 of appreciation on top of the $80,000 you borrowed, which is why the equity line runs the other way.
Priced at 6.875% on Schools to Home and 6.625% on the 3% down loan — a CHFA bond-funded first mortgage prices above a market conventional loan, which is the trade you make for the assistance — with PMI at 0.50% a year. These are illustrative, not quotes. Change any of them above and every figure on this page moves with it.
Schools to Home Ahead
80% first mortgage, no mortgage insurance, state second covers the rest.
- Cash at closing
- $0
- Monthly payment
- $2,399
- Mortgage insurance
- none
- Your appreciation share
- Equity when you sell
- $103,629
Conventional 3% down Behind
You fund the down payment and carry PMI until you reach 80%.
- Cash at closing
- $12,000
- Monthly payment
- $3,061
- PMI, drops off
- $162/mo, gone year 12
- Your appreciation share
- none — you keep it all
- Equity when you sell
- $138,990
Where it flips
How far ahead Schools to Home leaves you, by how fast the home gains and how long you stay. Green means it wins.
Read across a row and the pattern holds: the assistance is worth most when the home gains slowly, and least when it climbs fast. At 3% a year it stays ahead for the whole thirty. At 6% a year it stops winning around year 15, and by year 30 the share has cost more than the help was worth.
The 0% and −2% rows match on purpose. A home that has not gained owes no share either way, so below zero the advantage stops moving — the assistance costs you nothing but the repayment.
How the share is figured
CHFA sets your share once, at closing, and it never changes.
- You buy at $400,000. The first mortgage is 80% of that, $320,000 — the reason there is no mortgage insurance.
- The state second is $80,000. That is 25.0% of the first mortgage, and 20.0% of the purchase price.
- Your share is that second divided by the price: 20.0%. It is locked at closing and never moves.
- Sell in year 7 for $491,950 and the gain is $91,950.
- You owe the $80,000 back, plus 20.0% of that gain — $18,390. Total $98,390.
- Nothing is due until you sell, refinance, pay off the first, or stop living there.
What this assumes
- The first mortgage is 80% of the purchase price, which is what keeps mortgage insurance off the loan. The state second covers up to 25% of that first mortgage — 20% of the price. Take less and you bring the difference in cash.
- Your appreciation share is the original second divided by the original purchase price, applied to the gain between your purchase price and your sale price. A home that loses value owes no share, but the second is still repaid in full.
- Both loans are 30-year fixed and amortized properly, so the payoff figures sit slightly below CHFA's own illustration, which uses the opening balance.
- PMI on the 3%-down loan is removed once the balance amortizes down to 80% of the purchase price. That is the automatic rule. If the home climbs quickly you could cancel earlier by paying for an appraisal, which would narrow the gap — so this assumption leans slightly in Schools to Home’s favor.
- Taxes, insurance and HOA are identical in both columns, so they change the payment but never the comparison.
- Rates and mortgage insurance are assumptions, not quotes: 6.875% on the Schools to Home first mortgage, 6.625% on the conventional 3% down loan, and PMI at 0.50% of the loan balance per year. A 97% loan-to-value loan carries pricing adjustments an 80% loan does not, which is why the two rates differ. Your own quote depends on credit score, loan amount, property and the day you lock.
- Cash you keep at closing and each month of payment difference are counted at face value — no investment return, no tax effects.
- Selling costs are left out. They are the same either way.
Estimate only, not a commitment to lend or a quote. Rates, mortgage insurance and program terms change. CHFA sets Schools to Home terms — including income limits, a 620 minimum credit score, full-time employment at an eligible Colorado public school employer, and two required education courses — and verifies eligibility at application. Speak Straight Mortgage · Company NMLS 2426226 · Equal Housing Opportunity.
Prefer it on its own page? Open the Schools to Home estimator.
Keep reading
See if your school qualifies
Answer a few quick questions about your situation — no hard credit pull, no pressure. We'll confirm your eligibility for CHFA Schools to Home and map out your options.
Check my eligibility