Colorado Down Payment Assistance 2026: Every Program, Who Qualifies, and What You Repay
About twenty Colorado down payment programs, sorted by who they are for and whether you ever pay the money back. Includes a finder that checks your score, county, income and loan term.
 Matt WentzMay 12, 2025
The short version. Colorado has about twenty down payment programs, and they are four different things wearing the same name. Grants of 2% to 3.5% that you never repay. Forgivable seconds of 3.5% to 5% that disappear after 36 or 60 on-time payments. CHFA's deferred seconds of up to 4% (and up to 25% for school employees) that you repay when you sell. Repayable seconds with a small monthly payment. Most need a 620 to 640 score, many waive the income limit for first-time buyers, first responders, educators and healthcare workers, and only some allow a 25-year term.
Saving a down payment while rent keeps going up can feel like running on a treadmill that speeds up every time you get close. Then you go looking for help and find a wall of program names, each one promising thousands of dollars, and no way to tell which ones you can actually use or what they cost you later.
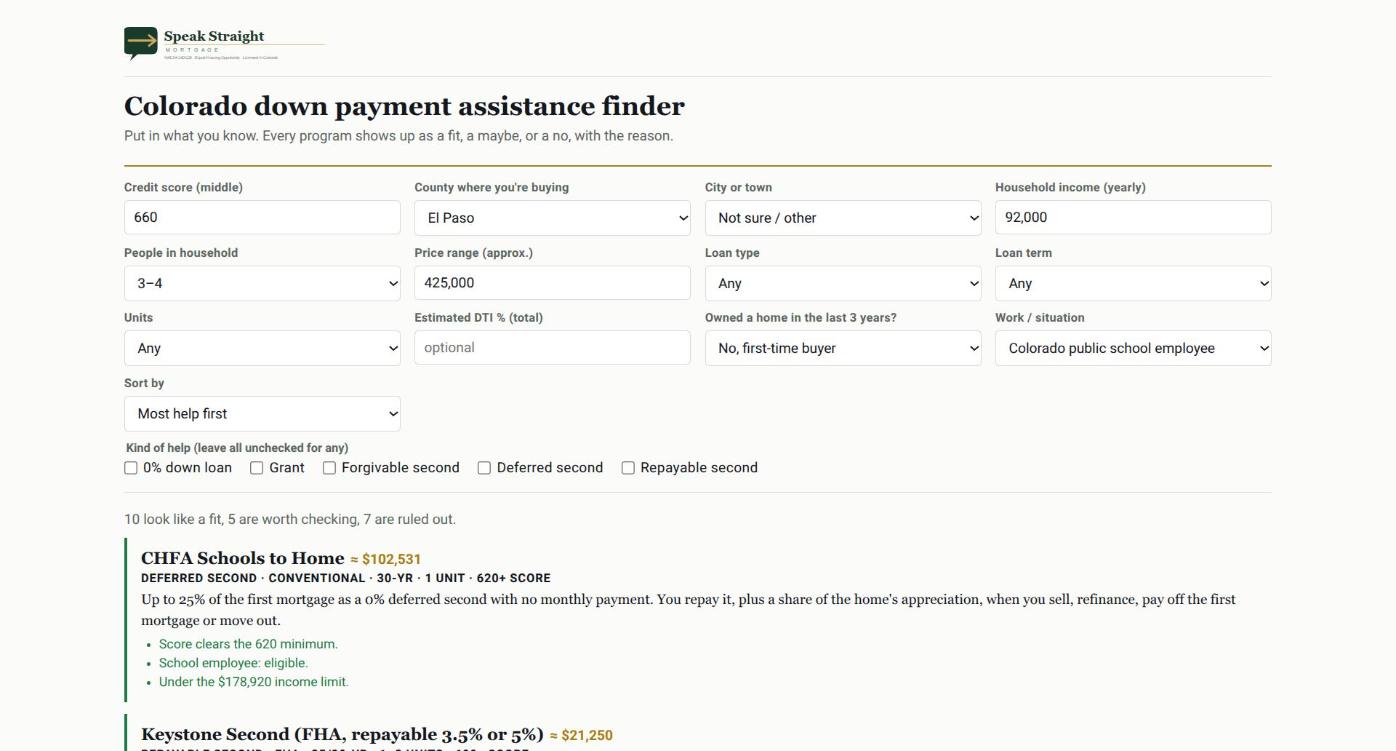
This guide is the list we work from. It covers every program we offer in Colorado, who each one is for, and the part most guides skip: whether the money is a gift, a loan that goes away, or a loan you pay back. Put your own numbers in the finder below and it sorts every program into a fit, a maybe or a no, with the reason.
First, the four kinds of help
Grant. Money toward your down payment or closing costs that you never repay, with no lien on the house. Our grants run 2% to 3.5% on FHA and 1% to 3% on conventional loans. One catch on one of them: pay the whole loan off inside your first six payments and the grant gets added back.
Forgivable second. A 0% second mortgage with no payment that is forgiven after a streak of on-time payments on your first mortgage. The streak is 36 payments on two of ours and 60 on another, and a late payment can restart it. Sell or refinance before then and you pay it back.
Deferred second. A 0% second with no monthly payment that you repay when you sell, refinance, pay off the first mortgage or move out. This is how CHFA's "Plus" programs work. Schools to Home is a deferred second too, plus a share of the home's appreciation.
Repayable second. A second mortgage with a real monthly payment, usually over 10 to 15 years at a rate a little above your first mortgage. It counts in your debt-to-income ratio. It is often the easiest one to qualify for, and the right answer when the others do not fit.
And one that is not assistance at all: USDA finances 100% of the price, so there is no down payment to help with. It covers most of rural Colorado and a lot of the suburbs, under an income limit by county. Core cities like Denver, Colorado Springs, Fort Collins and Boulder are not eligible, but many towns and neighborhoods just outside them are. Check any address on USDA's map or read how USDA loans work.
Find the programs that fit you
Enter what you know. Leave anything blank you are not sure of. Nothing is saved and nothing touches your credit.
The finder is a first look, not an approval. Income is counted the way each program counts it, and your loan officer confirms every number.
If you work in a school
You spend your days showing up for other people's kids, and a lot of school employees quietly assume owning a home in the community they serve is out of reach. This program was written to change that.
CHFA Schools to Home is the biggest program in the state for anyone who qualifies: up to 25% of the first mortgage, enough to reach 20% equity and drop monthly mortgage insurance. It is open to full-time employees of Colorado preK-12 public schools, districts and charter schools, teachers or not, and only one buyer needs to qualify. You do not have to be a first-time buyer. Household income has to be at or under $178,920, credit 620 or higher, on a 30-year conventional loan.
You do repay it, with a share of the home's appreciation when you sell, refinance or move out. On the right home that trade is well worth it. On others a 3.5% grant leaves you ahead. That comparison is the one to make with a loan officer before you choose.
If you are a first responder, in healthcare, military or public service
You run toward the hard calls for everyone else. When it is your turn to buy, it can be frustrating to find out your overtime pushed you over an income limit you did not know existed. These two skip that limit for you.
Two down payment grants of up to 3.5% waive their income limit for active or retired police, fire, EMS and public safety (volunteers included), educators, healthcare workers, civil servants and military. Neither requires a first-time buyer. One starts at a 620 score on FHA. The other needs 640 on FHA, or 620 on a conventional loan at up to 3%.
If your parents never owned a home
Being the first in your family to buy means there is nobody at the dinner table to ask how any of this works. That is exactly who these programs are for, and they are some of the most generous in the state.
CHFA FirstGeneration Plus adds $25,000 as a deferred second for buyers whose parents or guardians never owned during their lifetime (there is a foster-care exception). Everyone on the loan has to be a first-time buyer and complete a homebuyer class. In the City and County of Denver, Denver First Generation adds $30,000 (up to 20% of the price) as a 0% second you repay when you sell or refinance, and it can cover your agent's commission. It has a tighter debt limit than most programs: 43% of income in total and 38% for the house payment.
If someone in the household has a disability
A home that works for the person you care for matters more than square footage, and the budget is usually already stretched. This one is built for that.
CHFA HomeAccess Plus adds up to $25,000 as a deferred second when a buyer, or a dependent who lives in the home at least half the time, has a permanent disability. It works with FHA, VA and USDA, needs only $500 from you, and allows a cosigner.
Everyone else
If none of the groups above sound like you, you have not missed out. Most of the help in Colorado has no job, family or first-time requirement at all.
CHFA SmartStep Plus gives a 3% grant or a 4% deferred second on FHA, VA or USDA, capped at $25,000, with an income limit of $178,920 and no first-time-buyer rule. CHFA Preferred Plus offers up to 4% on a conventional loan, with lower mortgage insurance when your income is at or under 80% of the area median. Across the Denver metro and Northern Colorado, Metro Down Payment Assistance adds 3% or 4% of the loan as a no-payment second on FHA, VA, USDA or conventional loans. It is never forgiven, but it has no first-time-buyer rule, no price limit, and a $216,000 income limit on most versions. For lower scores or higher incomes, the FHA seconds (Keystone, Kiowa, Ouray and Orchard) offer 3.5% or 5%, with no income limit on most versions and scores from 600 to 660.
By credit score
A score you are embarrassed about is one of the most common reasons people never ask. Here is where each range actually stands. 600 to 619: the Keystone and Kiowa FHA seconds. 620 to 639: add every CHFA program, Metro DPA, and the 620 grant. 640 to 659: add the second grant on FHA. 660 and up: add the Ouray and Orchard seconds. Under 600, the honest answer is a credit plan first, and we build those too.
Eligible is not the same as approved
If you have been turned down somewhere else with a score that should have worked, you probably felt like the door just closed, and you were left wondering what you did wrong. Usually it was not you.
A credit score makes you eligible for a program. Approval depends on how the whole loan is put together: the term, which program carries the down payment, how income is counted, which debts are paid off at closing, and whether the seller covers some costs. Two loan officers can look at the same buyer with the same score and get two different answers.
Some real examples of what changes the outcome. A buyer declined on a 30-year loan can sometimes be approved on a 25-year term. A program with a payment-free second can clear a debt-to-income limit that a repayable second breaks. Overtime, a second job or a co-borrower who will not live in the home can count with one program and not another. Paying off one small card at closing can change an automated decision.
And not every lender has every program. Many offer one or two of the programs on this page, and some offer none. Even when two lenders carry the same program, knowing how to structure the loan to fit it is a skill, and it is the part that turns a no into a yes. If you have heard no before, it is worth a second look.
Income limits by county, 2026
CHFA limits are effective June 15, 2026. USDA limits are effective July 13, 2026, and count everyone who lives in the home, not just the borrowers. FirstStep and FirstGeneration limits are higher in CHFA's targeted areas.
| County | CHFA SmartStep, Preferred, Schools to Home | CHFA FirstStep & FirstGeneration (1–2 / 3+ people) | FirstStep & FirstGeneration price limit | USDA (1–4 / 5–8 people) |
|---|---|---|---|---|
| El Paso | $178,920 | $127,800 / $146,970 | $566,730 | $133,850 / $176,700 |
| Teller | $178,920 | $127,800 / $146,970 | $566,730 | $130,250 / $171,950 |
| Pueblo | $178,920 | $153,360 / $178,920 | $692,210 | $130,250 / $171,950 |
| Denver | $178,920 | $144,000 / $165,600 | $832,750 | $153,550 / $202,700 |
| Adams | $178,920 | $144,000 / $165,600 | $832,750 | $153,550 / $202,700 |
| Arapahoe | $178,920 | $144,000 / $165,600 | $832,750 | $153,550 / $202,700 |
| Jefferson | $178,920 | $144,000 / $165,600 | $832,750 | $153,550 / $202,700 |
| Douglas | $178,920 | $144,000 / $165,600 | $832,750 | $153,550 / $202,700 |
| Elbert | $178,920 | $144,000 / $165,600 | $832,750 | $153,550 / $202,700 |
| Boulder | $178,920 | $150,000 / $172,500 | $832,750 | $153,550 / $202,700 |
| Larimer | $178,920 | $130,400 / $149,960 | $664,190 | $149,950 / $197,950 |
| Weld | $178,920 | $153,600 / $179,200 | $735,320 | $143,600 / $189,600 |
| Mesa | $178,920 | $127,800 / $146,970 | $566,350 | $130,250 / $171,950 |
Who allows a 25-year loan
A 25-year term pays the house off five years sooner for a higher payment. These allow it: Evergreen Grant, Overlook Grant, Keystone Second, Kiowa Second, Orchard Second. Every CHFA program, Metro DPA, Ouray and the conventional grants are 30-year only.
Things that catch people
CHFA finances one living unit only, so no duplexes (a home with an ADU still counts as one unit if the appraiser says so). Several FHA programs allow two units. Most programs require a homebuyer education class before closing, so take it early. A repayable second's payment counts against your debt-to-income ratio. And the most common mistake, the one that stings years later: picking a program by the biggest number instead of by what you owe when you sell.
Every program, side by side
| Program | Kind of help | Amount | Loan | Term | Units | Min score | Income limit | First-time buyer? |
|---|---|---|---|---|---|---|---|---|
| CHFA Schools to Home | Deferred second | Up to 25% | Conventional | 30-yr | 1 | 620 | $178,920 | No |
| CHFA SmartStep Plus (grant) | Grant | Up to 3% (max $25,000) | FHA, VA, USDA | 30-yr | 1 | 620 | $178,920 | No |
| CHFA SmartStep Plus (second) | Deferred second | Up to 4% (max $25,000) | FHA, VA, USDA | 30-yr | 1 | 620 | $178,920 | No |
| CHFA FirstStep Plus | Deferred second | Up to 4% (max $25,000) | FHA | 30-yr | 1 | 620 | By county and household size | Outside targeted areas |
| CHFA FirstGeneration Plus | Deferred second | $25,000 | FHA | 30-yr | 1 | 620 | By county and household size | First-generation only |
| CHFA Preferred Plus | Deferred second | Up to 4% (max $25,000) | Conventional | 30-yr | 1 | 620 | $178,920 | No |
| CHFA Preferred Plus (very low income) | Deferred second | Up to 4% (max $25,000) | Conventional | 30-yr | 1 | 620 | County very-low-income limit | No |
| CHFA HomeAccess Plus | Deferred second | Up to $25,000 | FHA, VA, USDA | 30-yr | 1 | 620 | $178,920 | No |
| Metro Down Payment Assistance (FHA/VA/USDA) | Deferred second | 3% or 4% | FHA, VA, USDA | 30-yr | 1–2 | 620 | $216,000 | No |
| Metro Down Payment Assistance (conventional, ≤80% AMI) | Deferred second | 3% or 4% | Conventional | 30-yr | 1–2 | 620 | 80% of area median, by county | No |
| Metro Down Payment Assistance (conventional, over 80% AMI) | Deferred second | 3% or 4% | Conventional | 30-yr | 1–2 | 620 | $216,000 | No |
| Denver First Generation (metroDPA) | Deferred second | $30,000 (max 20% of price) | FHA | 30-yr | 1–2 | 620 | $100,800 (1 person) to $190,100 (8), whole household | First-generation only |
| Evergreen Grant (FHA, 2% or 3.5%) | Grant | 2% or 3.5% | FHA | 20 / 25 / 30-yr | 1–4 | 620 | ≤140% of area median, waived for first-time buyers and many jobs | No |
| Overlook Grant (FHA, 2% or 3.5%) | Grant | 2% or 3.5% | FHA | 25 / 30-yr | 1–2 | 640 | ≤160% of area median, waived for first-time buyers and many jobs | No |
| Overlook Grant (conventional, 1–3%) | Grant | 3% | Conventional | 30-yr | 1–4 | 620 | ≤160% of area median, waived for first-time buyers and many jobs | Only under 5% down |
| Keystone Second (FHA, repayable 3.5% or 5%) | Repayable second | Up to 5% | FHA | 25 / 30-yr | 1–2 | 600 | None | No |
| Keystone Second (FHA, forgivable 3.5% or 5%) | Forgivable second | Up to 5% | FHA | 25 / 30-yr | 1–2 | 600 | None | No |
| Kiowa Second (FHA, 3.5% forgiven in 3 years) | Forgivable second | 3.5% | FHA | 25 / 30-yr | 1–2 | 600 | Being confirmed | No |
| Kiowa Second (FHA, repayable 3.5% or 5%) | Repayable second | Up to 5% | FHA | 25 / 30-yr | 1–2 | 600 | Being confirmed | No |
| Orchard Second (FHA, 3.5% or 5%) | Forgivable second, Repayable second | 3.5% or 5% | FHA, USDA | 25 / 30-yr | 1–2 | 660 | None | No |
| Ouray Second (FHA, 3.5% or 5%) | Forgivable second, Repayable second | 3.5% or 5% | FHA | 30-yr | 1–2 | 660 | None on repayable; ≤160% of area median on forgivable | No |
| USDA Rural Development loan (0% down) | 0% down loan | 100% financing | USDA | 30-yr | 1 | 640 | USDA county limit | No |
Program facts as of 2026-10-10. Programs change; we update this page when they do. Wholesale programs are shown by the names we use for them.
There are a lot of options. One of them fits you best. The right choice depends on the home, your income, your plans and how long you will stay, and sorting that out takes a conversation with someone who knows every program. We go through it with you, free, with no hard credit pull. Book a time or call us at (720) 915-0334.
Questions people ask
Is down payment assistance in Colorado free money?
Some of it is. A grant is never repaid. A forgivable second goes away after a set number of on-time payments (36 or 60, depending on the program). A deferred second has no payments, but you pay it back when you sell or refinance. A repayable second has a small monthly payment. Ask which one you are being offered before you choose.
Do I have to be a first-time buyer?
For most of these programs, no. CHFA FirstStep needs a first-time buyer outside targeted areas, and the first-generation programs need buyers whose parents never owned. The grants, CHFA SmartStep, Preferred and Schools to Home do not require it.
What credit score do I need for down payment assistance in Colorado?
Some FHA programs start at 600. CHFA programs need 620, one grant needs 640, and two of the FHA seconds need 660. Below 600, the path is a credit plan first.
Can I get down payment assistance on a 25-year loan?
Yes, on these: Evergreen Grant, Overlook Grant, Keystone Second, Kiowa Second, Orchard Second. CHFA and the conventional programs are 30-year only.
Can I buy a duplex with down payment assistance?
CHFA programs are one living unit only. Several FHA programs allow two units, and two of the grants allow up to four on the right loan.
What is CHFA Schools to Home?
A CHFA program for full-time employees of Colorado preK-12 public schools, districts and charter schools. It lends up to 25% of the first mortgage as a deferred second with no monthly payment. You repay it, plus a share of the home's appreciation, when you sell, refinance or move out. Income limit $178,920, 620 credit.
Is there down payment help for first responders in Colorado?
Yes. Two grants of up to 3.5% waive their income limit for police, fire, EMS and public safety, active or retired, volunteers included. Educators, healthcare workers, civil servants and military get the same waiver.
Is there a 0% down option?
USDA loans finance 100% of the price in eligible rural and suburban areas, under a household income limit by county. VA loans are 0% down for eligible veterans and service members.
Frequently Asked Questions
Is down payment assistance in Colorado free money?
Do I have to be a first-time buyer?
What credit score do I need for down payment assistance in Colorado?
Can I get down payment assistance on a 25-year loan?
Can I buy a duplex with down payment assistance?
What is CHFA Schools to Home?
Is there down payment help for first responders in Colorado?
Is there a 0% down option?
Questions about your situation?
Get straight answers on a free Gain Clarity call — no pressure, no obligation.
Book your free call